The best net-worth tracker for expats and people with money in two countries
Seven trackers that connect to banks in more than one country and convert currencies properly, plus the popular apps that do not.


ASK AI
about kubera
about kubera
If you have a pension in one country, a brokerage in another and a bank in a third, most finance apps fail you on the first screen: they connect to one country’s banks and show one currency. This is a list of the ones that do not, with the facts on each, and a short list of popular apps that are wrong for this job so you can stop evaluating them.
Three things decide whether a tracker works across borders. Which aggregators it uses, because each one covers different countries (Plaid and Yodlee for North America and some of Europe, Salt Edge for the UK and EU, Akahu for New Zealand, Basiq for Australia, Lean for the Gulf). Whether an asset can be held in its own currency and converted to a base currency you choose. And whether the things no aggregator reaches, a foreign pension or a flat, can be kept current without re-typing.
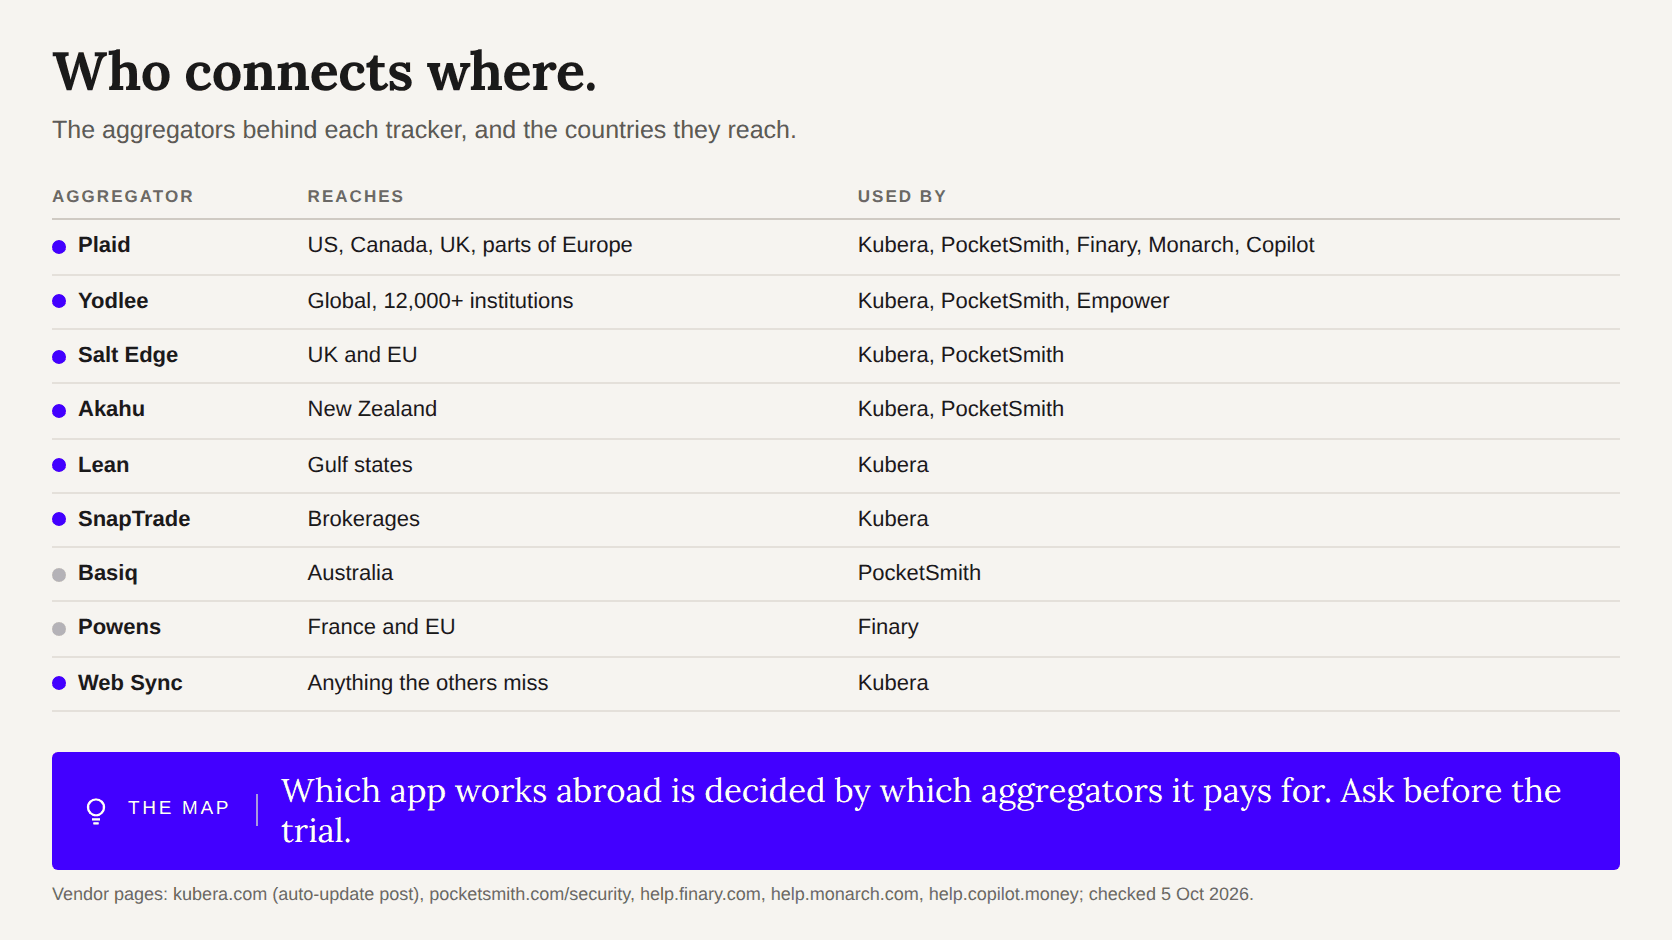
Nine aggregators (Plaid, Yodlee, MX, Akoya, Mastercard, Salt Edge, Lean, Akahu, SnapTrade) plus in-house connections: 20,000+ institutions across 40+ countries, including the UK, Ireland, Germany, Italy, Spain, the Netherlands, Sweden, UAE, India, Singapore, Hong Kong, Malaysia, South Africa, Australia and New Zealand. Any asset in any currency, converted at rates refreshed every two hours. Web Sync for banks no aggregator reaches. Crypto, property, private investments and debts on the same page.
A share-portfolio tracker covering 60+ markets and over 100 currencies, reporting in the currency of your tax residence. Investments only: no bank aggregation, no liabilities, so no net worth. The multi-currency valuation report needs the Standard plan.
A budgeting and forecasting app with bank feeds through Yodlee, Plaid, Salt Edge, Akahu, Basiq and Mastercard (US, Canada, UK, Europe, Australia, New Zealand). Converts every account to one base currency, including BTC and gold.
A French wealth app for the EU: Powens and Plaid connections including Revolut, N26 and Wise; display in EUR, USD, CHF, GBP, SGD or CAD; a holding mode for entities on Pro.
Canada’s aggregator-first tracker: 20,000+ institutions claimed, US institutions on the Premium plan and up.
A net-worth tracker with 40+ currencies and 12,000+ banks claimed; the aggregators and countries behind that are not disclosed, and the Starter plan shows ads.
Any currency, any country, GOOGLEFINANCE for FX and share prices. Every balance typed by you.
Facts checked on 5 October 2026. Competitor prices and limits come from their own sites where they publish them; where they do not, the page says who reported the figure.
| Kubera | Sharesight | PocketSmith | Finary | Wealthica | Exirio | Spreadsheet | |
|---|---|---|---|---|---|---|---|
| Price | $250 / yr | Free–$279 / yr | From $120 / yr | €55–€350 / yr | $50–$250 / yr | $89–$275 / yr | Free |
| Countries | 40+ | 60+ markets (shares) | US, CA, UK, EU, AU, NZ | EU | Canada, US | Undisclosed | Any, by hand |
| Base currency | Any, converted | Tax residence | One base | 6 choices | CAD/USD | 40+ | Your formulas |
| Bank balances | Synced | Manual | Synced | Synced | Synced | Synced | Manual |
| Liabilities | Yes | No | Yes | Yes | Yes | Yes | Yes |
| Crypto | Exchanges, wallets, DeFi | Manual | Manual | Some | Exchanges | Some | Manual |
| Private investments | Schedules, IRR | Manual | Manual | Manual | Manual | Manual | Manual |
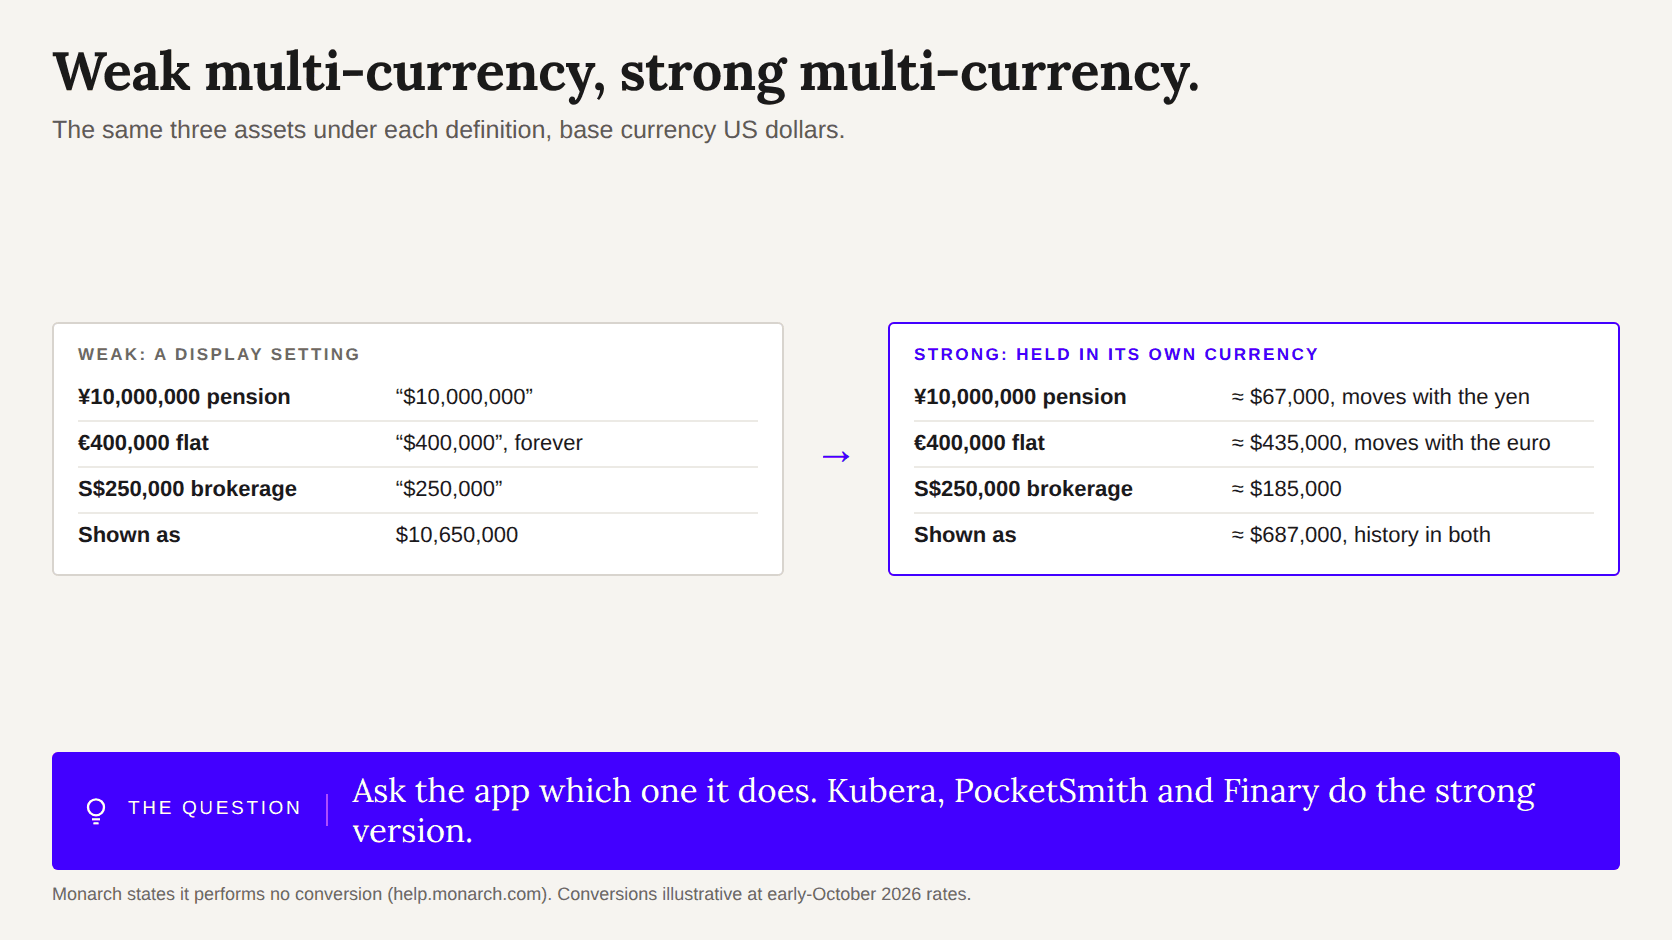
Empower Personal Dashboard connects to US institutions only and shows US dollars only; foreign accounts are manual entries. Monarch Money supports USD and CAD and performs no conversion, adding a ¥1,000 transaction as $1,000, and says it has no near-term plans to change that. Copilot Money is US institutions, US dollars, the US App Store. YNAB recommends a separate budget per currency. None of these is a bad app; each one is the wrong app for a person with money in two countries, and it is better to know that before the free trial.
Two different things get sold under the same word. The weak version is a display setting: the app shows a currency symbol and adds the numbers up. The strong version holds each asset in its own currency, converts at a current rate to a base currency you chose, and keeps the history in both. If your flat in Lisbon is worth €400,000 and your base is dollars, the strong version moves with the euro; the weak version shows $400,000 forever. Ask the app which one it does. Kubera, PocketSmith and Finary do the strong version; the table above says what the others do.
“I've lived in 3 countries and have bank accounts, investments, retirement accounts, and property in multiple locations and currencies. Kubera is the first time I've EVER been able to see my full financial picture in one place.”
“Its ability to seamlessly (and automatically) connect to foreign banks has been a lifesaver for me as someone living abroad.”
“Can't recommend Kubera enough - especially if one has accounts spread across different countries/currencies.”


