

Last reviewed November 20, 2026, against IRS Rev. Proc. 2026-35, FINRA and SEC investor guidance, lender rate sheets and the Federal Reserve Bank of New York.
"Buy, borrow, die" is a three-step way to turn investment gains into spending money without selling, and so without triggering capital gains tax. You buy assets that appreciate, borrow against them instead of selling, and hold them until death, when your heirs inherit them at a stepped-up cost basis and the lifetime gain is never taxed as income.
Every step is legal under current U.S. tax law, which is why the phrase shows up in tax-policy debates and on wealth-management sales pages. What gets less attention is whether it actually pays for a given investor. That depends on the loan rate, how long you borrow, how your investments perform, and whether you can survive a market crash without being forced to sell. This guide explains how each step works under 2026 rules, then runs the numbers: a 20-year example, the break-even interest rate, a stress test and a calculator you can use with your own figures.
What Is Buy, Borrow, Die?
The phrase was coined in the mid-1990s by USC law professor Edward McCaffery to explain to students how wealthy families avoid income tax over generations, according to USC Gould School of Law. It describes three steps:
- Buy assets that are likely to appreciate, such as stocks, real estate or a private business, and hold them. Gains aren't taxed until you sell.
- Borrow against those assets to fund spending or new investments, instead of selling. Loan proceeds aren't income, so no tax is due.
- Die holding the assets. Your heirs receive them with a cost basis equal to their market value at your death. The loans are repaid from the estate, often by selling some assets, and the gain built up during your life is never taxed as income.
The strategy is mainly used by people with large, highly appreciated portfolios: founders with company stock, long-term investors, and real estate owners. For someone with a modest portfolio, the interest and risk usually outweigh the tax saved.
How Each Step Works
Step 1: Buy and hold appreciating assets
The U.S. income tax generally taxes gains only when they are realized, usually by a sale. A stock bought for $1 million and now worth $10 million carries a $9 million unrealized gain, and you owe nothing on it until you sell. The longer you hold, the larger the untaxed gain and the more valuable the later steps become.
Dividends, interest and rent are still taxed each year. The strategy works best with assets whose return comes mostly from price growth, such as growth stocks, broad index funds with low yields, private company shares and appreciating real estate.
Step 2: Borrow against the assets instead of selling
Instead of selling to raise cash, you borrow and keep the assets invested. Common ways to borrow include:
- Securities-based lines of credit (SBLOCs). These are revolving lines secured by a taxable brokerage account, such as Schwab's Pledged Asset Line or Morgan Stanley's Liquidity Access Line (see our guides to pledged asset lines and the Liquidity Access Line). Rates are typically the Secured Overnight Financing Rate (SOFR) plus a spread that shrinks as the line gets bigger.
- Margin loans, which use the same collateral through a brokerage margin account and can be used to buy more securities.
- Mortgages, HELOCs and cash-out refinances secured by real estate.
- Custom loans from private banks against concentrated stock, art or other assets, usually at lower advance rates and higher spreads than an SBLOC.
SBLOCs are non-purpose loans: you can use the money for almost anything except buying or carrying securities, according to FINRA. Typical advance rates are 50% to 65% of the value of stocks, 65% to 80% for corporate bonds and up to 95% for Treasuries, according to a 2015 SEC and FINRA investor alert, and less against a single stock. Most lines are demand loans with monthly interest-only payments, and the lender can call them at any time.
You can't pledge an IRA or 401(k) as collateral for this kind of loan. Under IRS rules, pledging any part of an IRA as security treats that part as distributed, and therefore taxable. (A 401(k) plan loan is a separate, limited arrangement and doesn't serve this strategy.) Buy, borrow, die runs on taxable accounts, real estate and private holdings.
The interest is usually not tax-deductible when you borrow for living expenses. Deductibility follows how you use the money, not what secures the loan. Interest on money used to buy investment property, such as land held for investment, may be deductible as investment interest on Form 4952, but only up to your net investment income, which excludes qualified dividends and long-term gains unless you elect to have them taxed at ordinary rates. Interest on money used for a rental property or a business follows those activities' own rules.
Step 3: Heirs inherit with a stepped-up basis
Under Section 1014 of the tax code, property inherited from someone who dies generally takes a cost basis equal to its fair market value on the date of death. If your heirs sell soon after, there is little or no gain to tax. The appreciation that built up during your lifetime is never subject to income tax.
The step-up has limits:
- Retirement accounts don't get it. Traditional IRAs and 401(k)s are income in respect of a decedent, taxed as income when heirs withdraw.
- Lifetime gifts don't get it. Assets you give away while alive keep your original basis. And if someone gives you appreciated property and it comes back to them at your death within a year, there's no step-up.
- It can step down. An asset worth less than you paid takes the lower value, so the loss disappears.
- Some trusts don't get it. Assets in an irrevocable trust that isn't included in your estate don't receive a step-up, the IRS confirmed in Revenue Ruling 2023-2.
- Spouses are treated differently by state. In community property states, both halves of community property generally get a step-up when the first spouse dies. Elsewhere, jointly owned property typically gets a step-up only on the deceased spouse's half.
The loans don't disappear. The estate or the trust that owns the collateral repays them, usually by selling assets after death, when the step-up means little or no capital gains tax is due. Bona fide debts are also generally deductible from the estate's value for estate tax. Some families with grantor trusts use a power to swap assets so that low-basis holdings sit in the taxable estate at death and get the step-up; that takes an estate attorney.
Estate tax is separate and still applies
The step-up removes income tax on gains. It doesn't reduce estate tax. The federal estate and gift tax exemption is $15 million per person for 2026 and $15.48 million for 2027 under Rev. Proc. 2026-35, released November 5, 2026. A surviving spouse can add the deceased spouse's unused exemption through portability, but only by filing an estate tax return (Form 706) to elect it; the generation-skipping transfer tax exemption isn't portable. The 2025 tax law made the higher exemption permanent and indexed it for inflation. The value above the exemption is taxed at up to 40%. About a dozen states and Washington, D.C. levy their own estate taxes, often with much lower exemptions. See estate planning for the wider picture.
Is Buy, Borrow, Die Legal?
Yes. Each step is ordinary and permitted: holding appreciated assets, taking out a secured loan, and leaving property to heirs. There is no rule that requires you to sell assets to fund spending, and lenders routinely make these loans.
It is controversial. Critics call it a loophole that lets the very wealthy consume large fortunes while reporting little taxable income. Supporters of current law point out that the borrower pays real interest, carries real risk, and that the estate may still owe 40% estate tax. Several reform proposals target it directly (see "The policy debate in 2026" below). None has become law.
The Numbers: Selling vs. Borrowing
The case for borrowing is easiest to see in the first year. Assume a $10 million taxable portfolio with a $2 million cost basis, so 80% of its value is unrealized gain, and a need for $300,000 of spending money. The investor is in the top bracket for long-term gains, so federal tax is 20% plus the 3.8% net investment income tax, 23.8% in total, and there's no state tax.
Borrowing looks cheaper, $18,000 of interest instead of $70,553 of tax, but the comparison changes over time. Each year's tax is paid once, while the loan balance keeps growing as you borrow more and interest compounds.
A 20-year worked example
Now extend it. The same investor needs $300,000 a year, every year, for 20 years, then dies. The portfolio returns 7% a year, all from price growth. In one scenario, she sells enough each year to net $300,000 after tax. In the other, she draws $300,000 a year on a line of credit at 6% and never pays it down. Most lines bill interest monthly, and many expect it paid from a linked cash account. The model assumes she pays it by drawing more on the line, which needs spare credit and a lender willing to keep the line open for 20 years.
Borrowing leaves about $4.9 million more. Two effects produce it. The first is the tax: selling costs $1.6 million in capital gains tax, and the money paid in tax is no longer invested. The second is leverage: because the portfolio is assumed to earn 7% while the loan costs 6%, borrowing also profits from the spread. If the portfolio earned less than the loan rate, that second effect would work against you.
Both scenarios get the step-up at death, so heirs owe no capital gains tax on the remaining portfolio either way. If the estate is above the exemption, estate tax of up to 40% applies to both, which would shrink the $4.9 million gap to about $2.9 million.
Assumptions: $10 million portfolio, $2 million basis, $300,000 withdrawn or borrowed at the start of each year, a steady 7% annual return with no dividends, 23.8% federal capital gains rate, no state tax, each sale carrying a proportional share of basis, interest added to the loan. Selling the highest-basis lots first would lower the early tax bills and narrow the gap. Real returns vary year to year, which makes borrowing riskier than a steady path suggests. Illustrative only.

The break-even loan rate
The result is very sensitive to the interest rate, because a variable-rate loan compounds for decades.
In this example, borrowing still wins at a loan rate above the portfolio's 7% return, because selling costs about 19% of each sale in tax at first, rising to about 22% by year 20 as the gain grows. But the margin is thin at 8%, and a loan rate is not a promise. SBLOC rates reset with SOFR, whose 30-day average was about 3.9% in November 2026 according to the Federal Reserve Bank of New York, down from more than 5% through much of 2023 and 2024.
Returns matter just as much. At a 5% portfolio return and a 6% loan rate, borrowing's advantage falls to about $1.4 million and the loan-to-value ratio climbs to 44% by year 20. State taxes push the other way: a state tax on gains, up to 13.3% in California, makes selling costlier and raises the break-even rate.
Borrowing beats selling only while the tax you avoid is worth more than the interest you compound.
Buy, Borrow, Die Calculator
Test the trade with your own numbers. The calculator compares selling each year with borrowing each year, and shows the loan-to-value ratio and the break-even loan rate.
Borrowing Options Compared
SBLOC vs. HELOC
For a large portfolio, an SBLOC is often cheaper and faster than a HELOC. At SOFR of about 3.9%, Fidelity's published spreads put a $1 million to $3 million line near 6.25% and a $3 million-plus line near 5.8%, below the roughly 7.5% average HELOC. SBLOCs have no closing costs at many firms, interest-only payments, and funds in days.
A HELOC has one advantage: it isn't marked to market every day. A falling stock market can trigger a maintenance call on an SBLOC within days. A HELOC lender can freeze or reduce a line, but won't sell your house because the market dropped. Many borrowers use both, and see margin loan vs. mortgage for the trade-offs between portfolio and property debt.
The Risks of Buy, Borrow, Die
Maintenance calls and forced sales
If your pledged portfolio falls, the lender can require more collateral or a repayment, often within two or three days, FINRA warns. If you can't meet the call, the lender can sell your securities, which triggers exactly the capital gains tax you were avoiding, at the worst possible time.
In our example, here is what a 40% market fall would do to the loan-to-value ratio:
The risk grows with time because the loan keeps growing. A borrower in year 20 who hit a 2008-style crash would be at or near the 50%–65% that lenders typically advance against stocks, and likely over the limit on a concentrated position. There's no universal trigger: each lender sets its own limits by collateral and can lower them.

Other risks
- Rising rates. Most of these loans are variable. In our example, a rise from 6% to 8% cuts borrowing's advantage by almost two-thirds.
- Living longer than planned. Over 30 years at 6%, the loan in our example would reach $25 million. The strategy needs to end, at death or with a planned sale, before the debt overwhelms the portfolio.
- Concentration. Borrowing against one stock limits how much you can borrow and raises the chance of a call.
- Lender discretion. Many lines are payable on demand, and lenders can reduce what you can borrow against particular securities.
- Tax law changes. The step-up and the realization rule are policy choices that Congress could change.
- An estate without cash. Heirs may need to sell assets quickly to repay loans and pay estate tax, which is easier with liquid holdings than with real estate or a private business. Some families hold life insurance in an irrevocable life insurance trust (ILIT) to provide that cash outside the taxable estate.
- Reaching the borrowing limit. Once the loan reaches the lender's limit, you can't draw more, including to pay interest, so the plan stops working even before a maintenance call.
The Real Estate Version
Real estate investors use a related approach. They buy investment or business property, take depreciation deductions that reduce taxable rental income, refinance to pull out tax-free cash as values rise, and defer gains on sales through 1031 exchanges, which apply only to real property held for investment or business use. At death, heirs receive the property at a stepped-up basis. The deferred gains, including depreciation that would otherwise have been recaptured, generally escape income tax.
The same risks apply in a different form. Higher leverage, refinancing at higher rates, vacancies and falling property values can force a sale.
Who Buy, Borrow, Die Makes Sense For
It tends to fit investors who:
- Have a large taxable portfolio with a low cost basis, so selling would trigger a big tax bill.
- Need cash for spending or a purchase, but expect to keep most of their assets for life.
- Can keep the loan-to-value ratio low, typically well under 30%, with enough unpledged cash or income to meet a call.
- Hold assets likely to earn more than the loan costs over the long run.
- Are older, or have a planned end point, so the loan doesn't compound for decades.
- Have an estate plan that tells heirs where the assets and loans are and how the loans will be repaid.
It tends not to fit investors with high-basis assets, little cushion, concentrated positions, or short horizons for the money.
Alternatives to buy, borrow, die
There are often simpler options. Selling high-basis lots first, harvesting losses, giving appreciated shares to charity or a donor-advised fund, or spending from tax-deferred accounts in low-income years can cut the tax on selling without taking on debt. Holders of a concentrated, low-basis stock also look at exchange funds, which swap the position for a diversified fund without a sale; a charitable remainder trust, which sells tax-free inside the trust and pays an income stream; and hedging with collars or prepaid variable forwards.
The Policy Debate in 2026
Researchers disagree about how much buy, borrow, die matters in practice. A Tax Policy Center analysis by Edward Fox and Zachary Liscow found that annual borrowing by the top 1% equals only about 1% to 2% of their economic income, while their unrealized gains are 20 to 40 times larger. Their conclusion: the wealthy mostly hold and save, a pattern they call "buy, save, die," and the bigger issue is untaxed gains, not loans.
The Budget Lab at Yale modeled three reform options in 2025. Treating loans as a sale of appreciated assets would raise about $102 billion over 10 years, a 10% withholding tax on loan proceeds about $147 billion, and a 0.5% annual tax on covered loan balances about $130 billion.
Proposals in Congress include the ROBINHOOD Act, introduced by Sen. Ruben Gallego on June 2, 2026, with a House companion from Rep. Dan Goldman. It would treat taking out a loan as a realization event for taxpayers with income above $100 million or assets above $1 billion, according to Gallego's office. At the state level, California voters rejected Proposition 40, a one-time 5% tax on billionaires' net worth, in the November 3, 2026 election.
For now, the rules that make the strategy work are intact, and the 2025 tax law made the higher estate tax exemption permanent. See unrealized gains tax for more on taxing gains before a sale.
Tracking a Buy, Borrow, Die Plan in Kubera
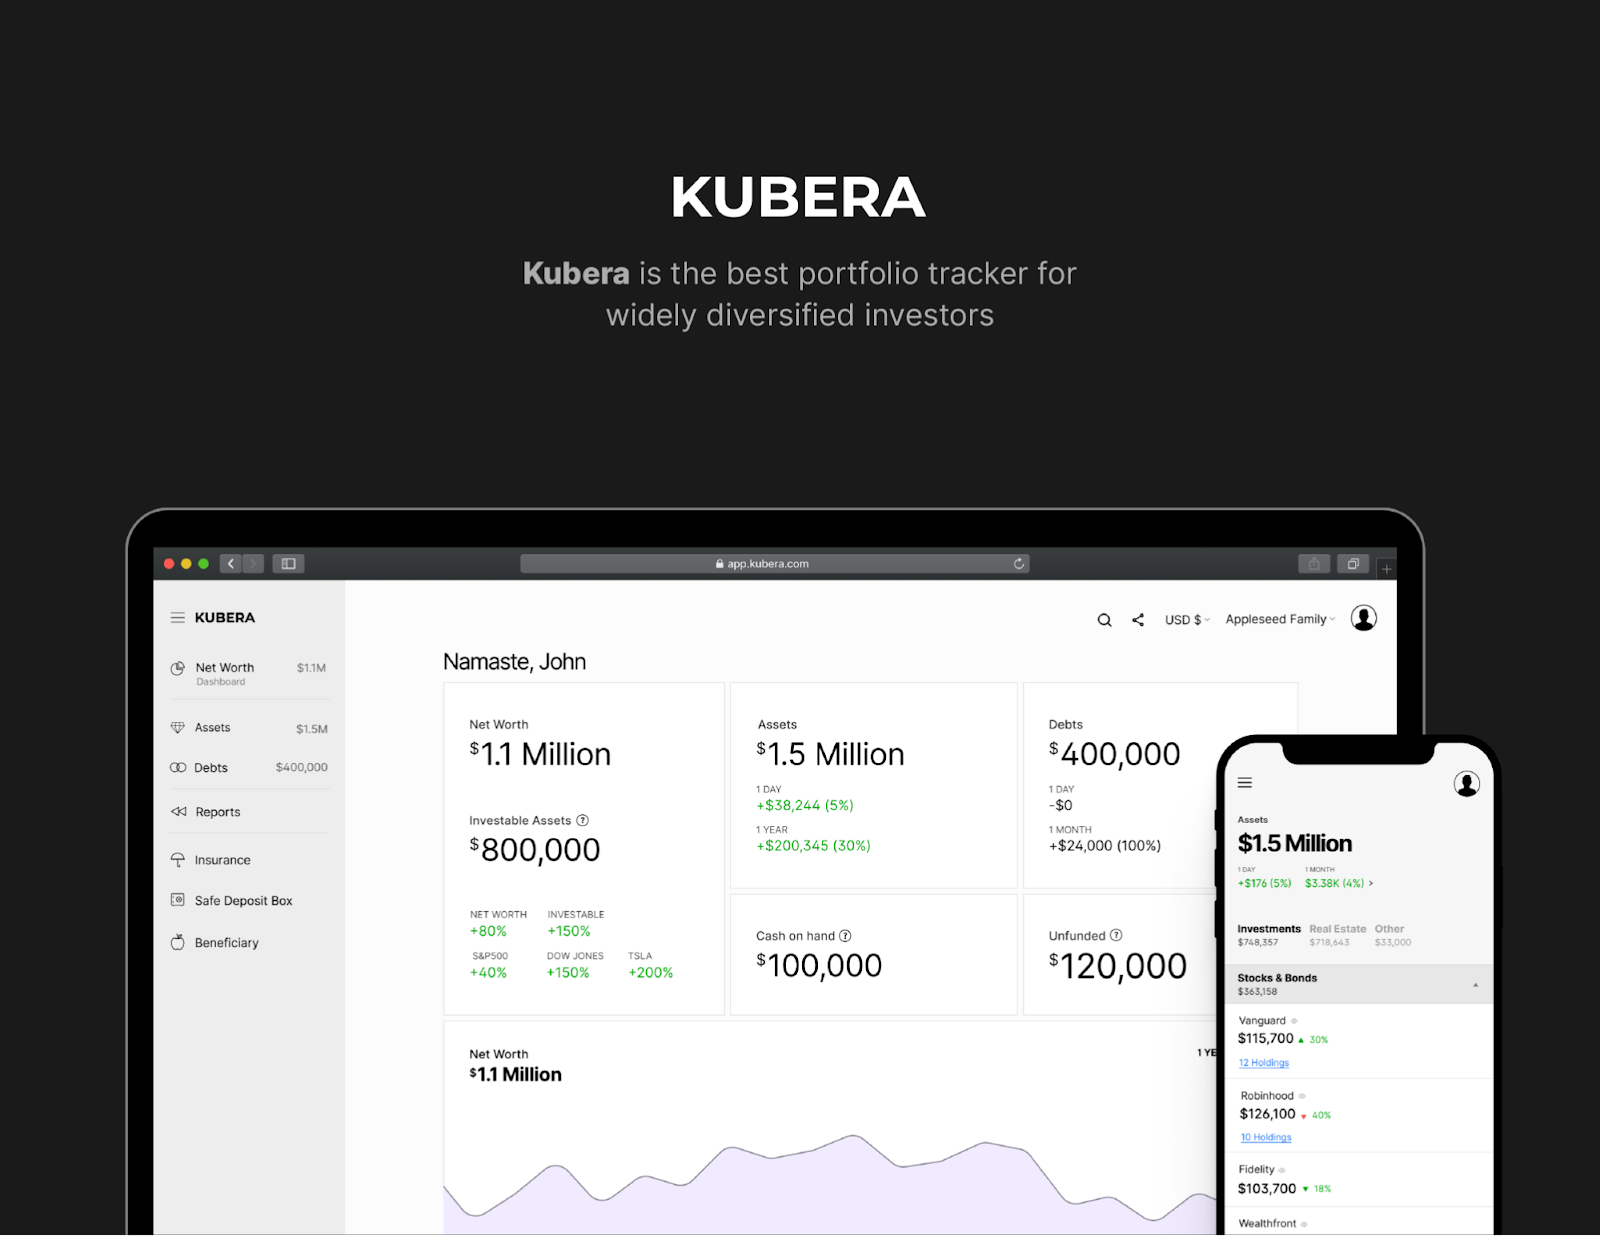
Buy, borrow, die runs on a handful of numbers that change every day: portfolio value, unrealized gains, loan balances and the ratio between them. Kubera puts them on one balance sheet. It doesn't lend money or give tax advice.
- See assets and loans together. Connect brokerage accounts and add SBLOCs, margin balances and mortgages as debts, so your net worth reflects what you owe as well as what you own.
- Watch your loan-to-value ratio. Compare pledged accounts with what you've drawn and spot a ratio creeping up before a lender does.
- Know your basis. Record cost basis and cash flows to see unrealized gains and returns on each holding, which tells you which assets are best to borrow against and which to sell first.
- Model the decades ahead. Fast Forward projects net worth with ongoing draws, interest and growth, so you can test a lower return or higher rate.
- Handle trusts and entities. On Kubera Black, ownership tags and nested portfolios separate assets held personally, jointly and in trusts, which matters for the step-up.
- Make the "die" step work. The Dead Man's Switch sends your portfolio, including the loans, to the people you choose if you go silent for too long, so your executor knows what has to be repaid.
Try it with a 14-day free trial.
Conclusion
Buy, borrow, die works because U.S. tax law doesn't tax loans or unrealized gains, and resets the basis of inherited assets. For an investor with a large, low-basis portfolio who borrows modestly, it can leave heirs millions more than selling. In our example, that was $4.9 million over 20 years.
It is also a leveraged bet on markets and interest rates. The advantage shrinks quickly as loan rates rise or returns fall, and a crash late in life can force the sale the strategy was meant to avoid. Keep the loan-to-value ratio low, plan for higher rates, know your cost basis, and make sure your heirs know about the loans. Work with a tax adviser and an estate attorney before relying on it.
Frequently Asked Questions
What is the buy, borrow, die strategy?
It's a way to fund spending from appreciated assets without selling them and triggering capital gains tax: buy assets that grow, borrow against them instead of selling, and hold them until death, when heirs inherit them at a stepped-up basis.
Who came up with buy, borrow, die?
USC law professor Edward McCaffery coined the phrase in the mid-1990s to explain how wealthy families avoid income tax across generations.
Is buy, borrow, die legal?
Yes. Holding appreciated assets, taking secured loans and leaving property to heirs are all permitted under current law. Lawmakers have proposed changes, but none has become law.
Can you do buy, borrow, die with an IRA or 401(k)?
No. Pledging an IRA as collateral is treated as a taxable distribution, retirement accounts can't back an SBLOC, and they don't get a step-up in basis at death. The strategy relies on taxable accounts, real estate and private holdings.
How much can I borrow against my portfolio?
Typical advance rates are 50% to 65% of the value of stocks, 65% to 80% for corporate bonds and up to 95% for Treasuries, and less against a single stock. Borrowing far less than the maximum leaves room for a market fall.
What interest rate makes buy, borrow, die worthwhile?
In our example, borrowing beat selling at any loan rate below about 8.9%, assuming a 7% return, an 80% unrealized gain and a 23.8% tax rate. A higher basis or lower returns lower the break-even rate; state taxes raise it.
What happens to the loans when I die?
They become debts of your estate. The executor usually repays them by selling assets, which by then have a stepped-up basis, so little or no capital gains tax is due. The loans also reduce the estate's value for estate tax.
Does the step-up in basis avoid estate tax?
No. The step-up removes income tax on gains. Estate tax is separate: in 2027, estates above $15.48 million per person pay up to 40% on the excess, and some states tax smaller estates.
Is SBLOC interest tax-deductible?
Usually not when you borrow for living expenses, because personal interest isn't deductible. Deductibility depends on how you use the money: interest on borrowing used to buy investment property may be deductible as investment interest, up to your net investment income.
Disclaimer
This article is general information as of November 20, 2026 and is not tax, legal or investment advice. Borrowing against investments involves the risk of loss, including forced sales. Interest rates, tax rules and lender terms change. Examples are illustrative and use simplified assumptions. Consult a qualified tax professional, estate attorney and financial adviser before using this strategy.


